A clear, practical guide to the biggest Social Security filing mistakes and how to avoid them, including Medicare timing, spousal and survivor rules, the ear...
Retirement is supposed to feel like exhaling. But when the numbers are a little tight, it can start to feel like you are holding your breath again.
The good news is you do not need a second career to create a little breathing room. The right part-time job or side hustle can cover groceries, property taxes, travel, or healthcare premiums while still leaving plenty of time for grandkids, golf, volunteering, or simply doing nothing at all.
Before you jump in: two quick guardrails
1) Protect your time first
If a job makes you dread Monday, it is too expensive. Look for flexibility, clear boundaries, and work you can stop doing if life changes.
2) Watch the ripple effects
- Social Security: If you are below full retirement age and taking Social Security, wages and net self-employment income above the annual limit can reduce benefits temporarily. (Once you reach full retirement age, the earnings limit goes away.) The withheld amounts are not “lost” forever, either. Your benefit is recalculated at full retirement age to credit months when benefits were withheld. Note: pensions and IRA withdrawals do not count as earned income for this test.
- Taxes and Medicare: Extra income can bump up your taxable income and, in some cases, affect Medicare premium surcharges (IRMAA). IRMAA is based on your modified adjusted gross income from two years prior, so a strong income year can show up later. It does not mean “do not work,” it just means plan for it.
- If you are not on Medicare yet: For early retirees buying coverage through the ACA marketplace, additional income can reduce premium tax credits, sometimes more than people expect. If you are 60 to 64 and using subsidies, confirm how extra income could change your net premium before you ramp up hours.
- Scams and overpromises: If someone wants you to pay a big fee up front to “unlock” earnings, walk away.
10 flexible, low-stress ways to earn extra retirement income
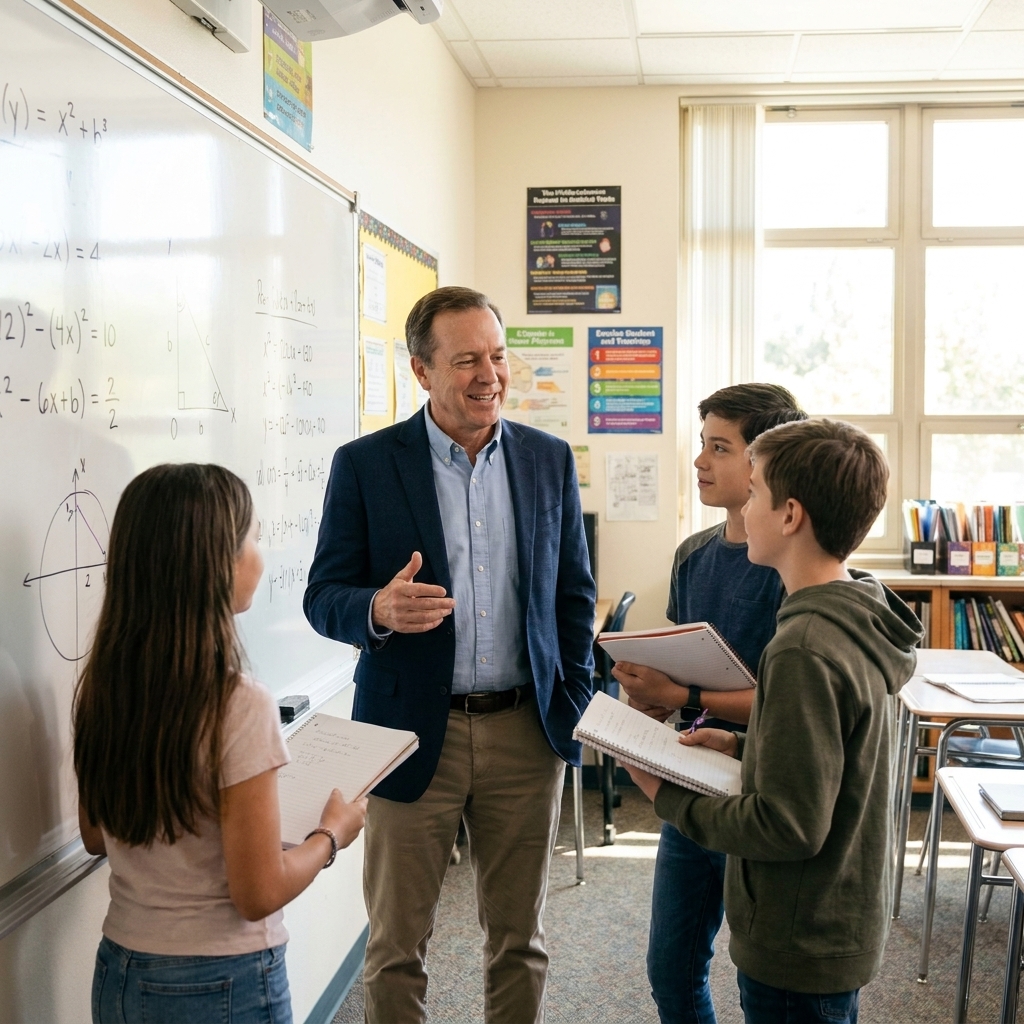
1) Substitute teacher or classroom aide
School districts often welcome dependable adults, and the schedule usually mirrors the school day and school year. In many places you can choose which days you accept assignments.
- Why retirees like it: Predictable hours, built-in breaks, purpose-driven work.
- Typical pay range: Pay varies a lot by district and credential. Many districts post daily rates that can range from about $100 to $250+ per day.
- Start-up costs: Background check, possibly a short training course.
- Good fit if: You like structure and do well managing a room.
2) Library, community center, or park district staff
These roles tend to be community-oriented and less sales-driven than typical retail. Think front desk help, program support, check-in staff, or event setup.
- Why retirees like it: Low pressure, friendly environment, consistent schedules.
- Typical pay range: Often starts in the mid-teens per hour and can climb into the low $20s depending on role and location.
- Start-up costs: Minimal.
- Good fit if: You enjoy helping people and prefer calm over chaos.
3) Seasonal work (tax season, holidays, local events)
Seasonal jobs can be perfect if you want income in short bursts. Retail is one option, but do not overlook local venues, museums, sports arenas, nurseries, and festivals.
- Why retirees like it: You can work a season, then stop.
- Typical pay range: Commonly in the mid-teens to mid-$20s per hour, with big swings by role and market. Some event roles pay per shift.
- Start-up costs: Usually none.
- Good fit if: You want income without a year-round commitment.
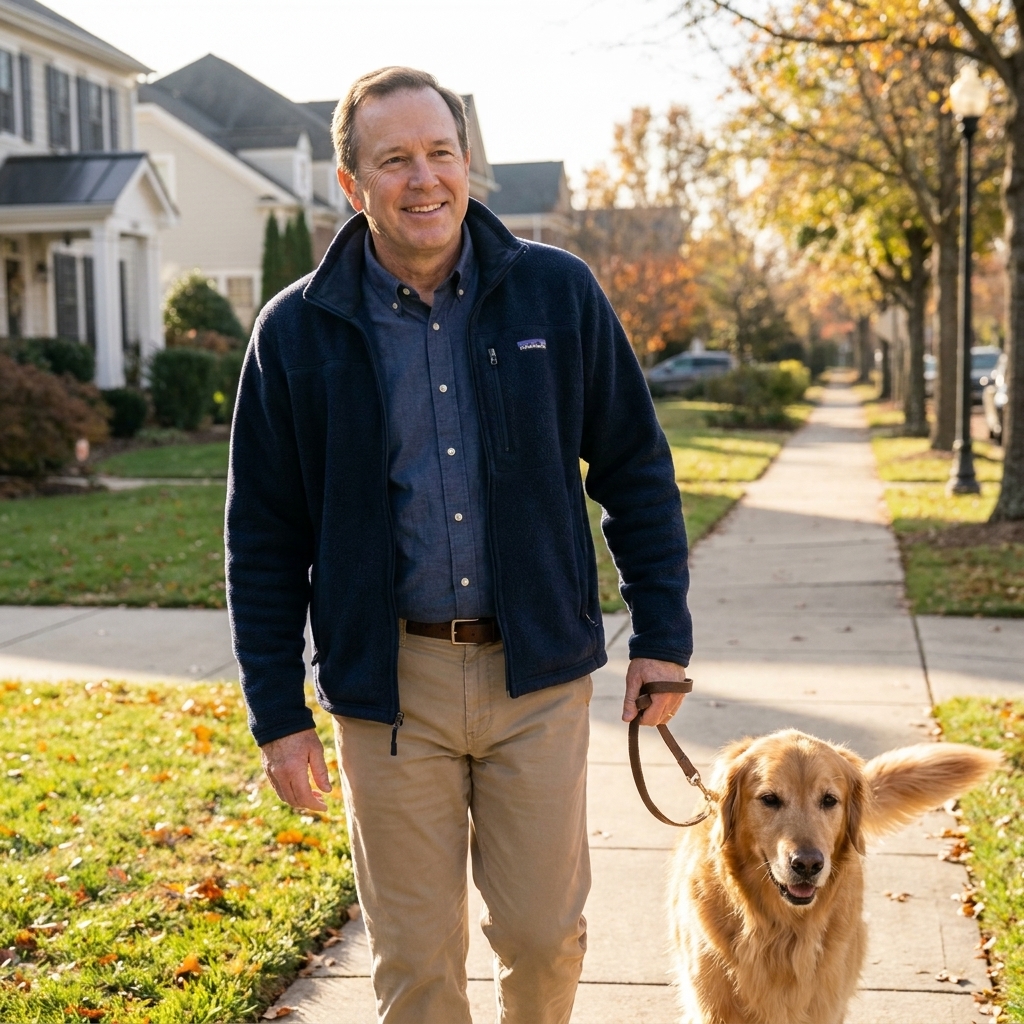
4) Pet sitting and dog walking
Like animals and steady routines? Pet sitting can be a wonderful fit. Some retirees build a small neighborhood client list. Others use reputable pet-sitting platforms to fill in the gaps.
- Why retirees like it: Flexible, active, often joyful work.
- Typical pay range: Market-dependent. Walks may range roughly $15 to $30 each, and overnight sitting can range widely based on location, holiday timing, and what is included.
- Start-up costs: Leash bags, basic supplies. Consider liability coverage if you go independent.
- Watch-outs: Be realistic about physical demands and weather. Also think through liability. A simple insurance policy can be cheaper than a single bad incident.
5) House sitting and home check services
Many families want someone to bring in mail, water plants, and keep an eye on the house while they travel. It is steady, low-impact work if you are reliable and comfortable with basic home tasks.
- Why retirees like it: Calm, simple duties, often close to home.
- Typical pay range: Varies widely, from a per-visit fee to a daily rate for longer sits.
- Start-up costs: Minimal. References matter more than fancy marketing.
- Good fit if: You are detail-oriented and trustworthy.
- Pro tip: Put expectations in writing. A short checklist covering pets, plants, mail, trash day, emergencies, and key handling prevents awkward misunderstandings later.
6) Handyman, honey-do helper, or light home maintenance
If you are the person friends call to fix a sticky door or hang shelves, this can turn into real income. Keep it light and safe: minor repairs, basic installations, seasonal prep, small projects.
- Why retirees like it: High demand, you control your schedule.
- Typical pay range: Rates vary dramatically by region, experience, and job type. Many independent helpers charge somewhere around $40 to $100+ per hour.
- Start-up costs: Tools you may already own. Consider insurance if you take on ongoing work.
- Watch-outs: Be careful with anything that can trigger licensing or permits. Electrical, plumbing, and HVAC work often has strict rules even for “small” jobs, and the line is not always obvious. When in doubt, stick to clearly non-regulated tasks or refer it out.
7) Tutoring, test prep, or conversation practice
You do not need to be a former teacher to tutor. Retired engineers tutor math. Retired nurses help students in anatomy. Retired managers coach interview skills. Even homework-helper sessions can be valuable for busy parents.
- Why retirees like it: Meaningful, mentally engaging, often remote.
- Typical pay range: Often $25 to $80+ per hour depending on subject, credentials, and market.
- Start-up costs: Minimal. A webcam and stable internet help if you work online.
- Good fit if: You like explaining things patiently.
- Pro tip: Use a simple intake form before the first session to learn goals, deadlines, learning style, and any areas of frustration. It saves time and makes you look incredibly professional.
8) Freelance writing, proofreading, or bookkeeping
If you are comfortable at a computer, service-based freelancing can be a strong quiet-income option. Businesses always need clean writing, polished resumes, accurate invoices, and someone to reconcile a few accounts.
- Why retirees like it: Work from home, choose clients, scalable hours.
- Typical pay range: Proofreading often falls around $20 to $45 per hour; bookkeeping frequently lands around $25 to $60+ per hour; writing varies widely based on niche and complexity.
- Start-up costs: Basic software, maybe a course if you want to refresh skills.
- Watch-outs: Set boundaries so it does not become a 24/7 email job.
9) Remote customer support (part-time)
Some companies hire part-time remote representatives for email, chat, or phone support. The best roles have clear shifts and solid training, so you are not improvising under pressure.
- Why retirees like it: Home-based work with predictable hours.
- Typical pay range: Commonly in the mid-teens to mid-$20s per hour depending on company and responsibilities.
- Start-up costs: Headset, reliable internet, sometimes a quiet workspace requirement.
- Watch-outs: Be selective. If the role is commission-heavy or feels like sales, it may be stressful.
- Pro tip: Ask whether the company provides equipment or a stipend. If not, price that into your decision.
10) Reselling and decluttering for profit
This can be especially appealing because it can start right in your own home. Sell what you no longer need, then decide if you want to keep going by sourcing items at estate sales or thrift shops.
- Why retirees like it: Flexible, can be a do-it-when-I-feel-like-it project.
- Typical pay range: Highly variable. Some people net a few hundred dollars a month; others build a serious side income over time.
- Start-up costs: Shipping supplies, basic storage bins, and a small budget if you start sourcing.
- Pro tip: Track mileage and expenses if you are doing it regularly.
Where to find good opportunities
- School roles: Your local school district website, substitute teacher staffing services, and district HR pages.
- City and county jobs: Library systems, park districts, and community centers often list part-time openings on municipal job boards.
- Retiree-friendly job boards: AARP’s job board can be a useful starting point for flexible roles.
- Word of mouth: For house sitting, pet sitting, tutoring, and handyman work, referrals from neighbors, faith communities, and local groups often beat any online ad.
- Freelance work: Start with people you already know. A simple “I have openings for two bookkeeping clients” email can do more than a dozen gig apps.
How to choose the right option for you
If you are torn between a few ideas, use these three questions to narrow it down:
- Do I want people time or quiet work? Substitute teaching and community roles are people-heavy. Freelance work is quieter.
- Do I want steady pay or project bursts? Remote support is steady. Seasonal work and reselling come in waves.
- What is my physical comfort level? Dog walking and handyman work can be great, but only if your body is on board.
The best retirement side hustle is the one you can do consistently without resentment.
Smart money habits for side hustle income
Separate it, so it feels real
Consider a dedicated checking account for side income. When money lands there, you can decide what job it needs to do: travel fund, emergency buffer, medical premiums, or extra investing.
Save for taxes if you are self-employed
If no one is withholding taxes for you, set aside a portion of each payment. Many retirees start with 20 percent to 30 percent in a separate savings bucket and adjust once they see how it shakes out at tax time. Also remember that 1099 income may be subject to self-employment tax (Social Security and Medicare taxes) in addition to regular income tax, depending on your situation.
Keep a simple paper trail
Track mileage, supplies, platform fees, and any training costs. You do not need a shoebox full of stress. A spreadsheet and a monthly routine work fine.
Think through basic protection
For pet sitting, house sitting, and handyman services, consider whether you need liability coverage, bonding, or a written agreement. A small amount of admin up front can prevent a big headache later.
FAQs retirees ask me all the time
Will working part-time reduce my Social Security?
If you are under full retirement age and receiving Social Security, wages and net self-employment income above the annual limit can temporarily reduce benefits. Once you reach full retirement age, the earnings limit no longer applies. The reduction is not permanent. Benefits are recalculated at full retirement age to credit months when benefits were withheld. If you are unsure where you land, check your Social Security statement or talk with a knowledgeable advisor before you ramp up hours.
Is it better to work a W-2 job or do a 1099 side hustle?
A W-2 job is often simpler because payroll handles withholding. A 1099 side hustle can be more flexible and may allow business deductions, but you are responsible for taxes, recordkeeping, and potentially self-employment tax. “Better” usually comes down to how much structure you want and how comfortable you are managing the admin.
Can side hustle income help my retirement plan long-term?
Absolutely. Even a few hundred dollars a month can reduce how much you need to withdraw from your portfolio early in retirement. That can make your savings last longer, which is the whole game.
A final neighborly nudge
If money feels tight, please hear this clearly: you are not failing. You are adapting. A flexible job that fits your life can turn a stressful budget into a sustainable one, without sacrificing the best part of retirement: freedom.
If you want help deciding which income idea fits your situation, start with your monthly gap number and your ideal weekly schedule. Once those are clear, the right side hustle usually becomes obvious.