Withdrawals from traditional retirement accounts can unexpectedly trigger taxes on Social Security. Here is how combined income works and how to plan smarter.
If you have ever opened your tax return and thought, “Wait, why am I paying taxes on my Social Security?” you are not alone. I used to see this all the time in HR benefits meetings: good, hardworking people did everything “right,” then got caught off guard when other income pushed them into the zone where Social Security becomes taxable.
The good news is that this is one of the most plannable parts of retirement taxes. The IRS uses a formula called provisional income to decide whether 0%, up to 50%, or up to 85% of your Social Security benefits are taxable. With a few legal strategies, you can often keep provisional income under key thresholds, or at least keep it from jumping around year to year.
One quick clarification that saves a lot of confusion: “up to 85% taxable” does not mean an 85% tax rate. It means up to 85% of your benefit may be included in taxable income, and then taxed at your normal marginal rate.
Provisional income basics
Think of provisional income as the IRS “gatekeeper” number. It is not the same as your taxable income.
Provisional income generally equals:
- AGI (excluding Social Security)
- + tax-exempt interest (like municipal bond interest)
- + 50% of your Social Security benefits
Some less common adjustments can apply, so if you want the official worksheet and edge cases, see IRS Publication 915 (Social Security and Equivalent Railroad Retirement Benefits).
Federal thresholds
Per IRS Publication 915, these are the key federal thresholds used to determine whether benefits are taxable:
- Single: $25,000 (starts taxation), $34,000 (up to 85% potentially taxable)
- Married filing jointly: $32,000 (starts taxation), $44,000 (up to 85% potentially taxable)
Important: these are federal rules and have been unchanged for decades. States vary widely. Many states do not tax Social Security at all, while a minority do (often with their own income limits and exemptions).
1) Use low-income years before claiming
If you are retiring at 62, 63, or 64 and you have not started Social Security yet, you may have a sweet-spot window where your income is temporarily lower. This can be a powerful time to intentionally recognize taxable income on your terms.
Two common examples:
- Roth conversions from a traditional IRA or 401(k)
- Realizing capital gains in a brokerage account, especially if you qualify for the 0% long-term capital gains rate
Why it helps: once Social Security starts, extra income can make your benefits taxable. Doing some tax work before you turn on Social Security can reduce future required minimum distributions (RMDs) and keep provisional income calmer later.
If you like a simple target, many households aim to “fill up” the 10% and 12% brackets during those in-between years, but the right number depends on your full picture.
One more important nuance: Roth withdrawals are often friendly for provisional income, but Roth conversions are taxable income in the year you do them. They can be great planning tools, but timing matters.
2) Choose a tax-smart withdrawal mix
Where your retirement paycheck comes from matters just as much as how much you withdraw. A mix of account types gives you levers to pull.
In simple terms:
- Traditional IRA/401(k) withdrawals often increase provisional income the most because they raise AGI dollar-for-dollar.
- Roth IRA withdrawals generally do not add to AGI, which often makes them friendlier for provisional income.
- Taxable brokerage withdrawals can be managed, because only the gains are taxable, and qualified dividends and long-term gains may be taxed at lower rates.
A practical approach many retirees use is to blend withdrawals rather than taking everything from one bucket. Your goal is to meet spending needs while keeping provisional income from jumping over a threshold by accident.
A mini-example to make the “threshold jump” real (numbers simplified, but the idea holds):
- Assume you are single and already receiving Social Security.
- You take an extra $1,000 from a traditional IRA late in the year.
- That $1,000 raises AGI by $1,000, which raises provisional income. If you are in the range where benefits are phasing into taxation, the formula can cause up to $850 of additional Social Security to become taxable.
- Result: your taxable income might increase by as much as $1,850 even though you only withdrew $1,000.
That is the “tax torpedo” effect people talk about: the Social Security formula can turn a small extra withdrawal into a larger increase in taxable income.
3) Use partial Roth conversions to cut RMDs
RMDs can be the quiet tax headache later in retirement. When RMDs begin, they can push up AGI, which pushes up provisional income, which can make more Social Security taxable.
Under current law, RMDs generally start at age 73 for people who reach age 72 after 2022. The starting age is scheduled to rise to 75 for people who reach age 74 after 2032. Because the rule depends on birth year and account type, it is worth confirming your exact start year before you build a plan.
A partial Roth conversion plan spreads conversions over multiple years. Instead of one big conversion (and one big tax bill), you convert enough each year to stay within a tax bracket you are comfortable with.
Why it helps Social Security taxes: smaller future RMDs can mean less forced income later, which can keep you below the thresholds that cause more of your benefit to be taxed.
Two cautions to keep in mind:
- Conversions increase income in the year you do them, so timing matters.
- Higher income can affect Medicare premium surcharges (IRMAA). It is not a reason to avoid planning, but it is a reason to plan carefully.
4) Plan capital gains on purpose
Capital gains can sneak up on Social Security taxation in two common ways: a big one-time sale (like rebalancing a long-held stock position) or a steady stream of gains from frequent trading.
Ideas to reduce the tax hit:
- Harvest losses when appropriate to offset gains.
- Spread a large sale over multiple tax years if you have flexibility.
- Use specific share identification to sell higher-basis shares when you want less gain.
Even when long-term capital gains get favorable rates, they still increase AGI and can increase provisional income. The goal is not “never realize gains,” it is to realize them with a plan.
5) Do not forget muni interest
This one surprises people. Interest from municipal bonds is often federal tax-free, but it still counts in the provisional income formula as tax-exempt interest.
So yes, a portfolio heavy in municipal bond funds can contribute to making your Social Security taxable even though that interest is not taxed the same way.
This does not mean municipal bonds are “bad.” It just means you should treat them like a real input in your Social Security tax planning. Also note that some municipal bond interest (such as certain private activity bond interest) can be relevant for the alternative minimum tax (AMT), so “tax-free” is not always as simple as it sounds.
For some households, shifting part of the bond allocation into tax-deferred space (like an IRA) or using other fixed-income options can reduce pressure on provisional income.
6) Use QCDs when eligible
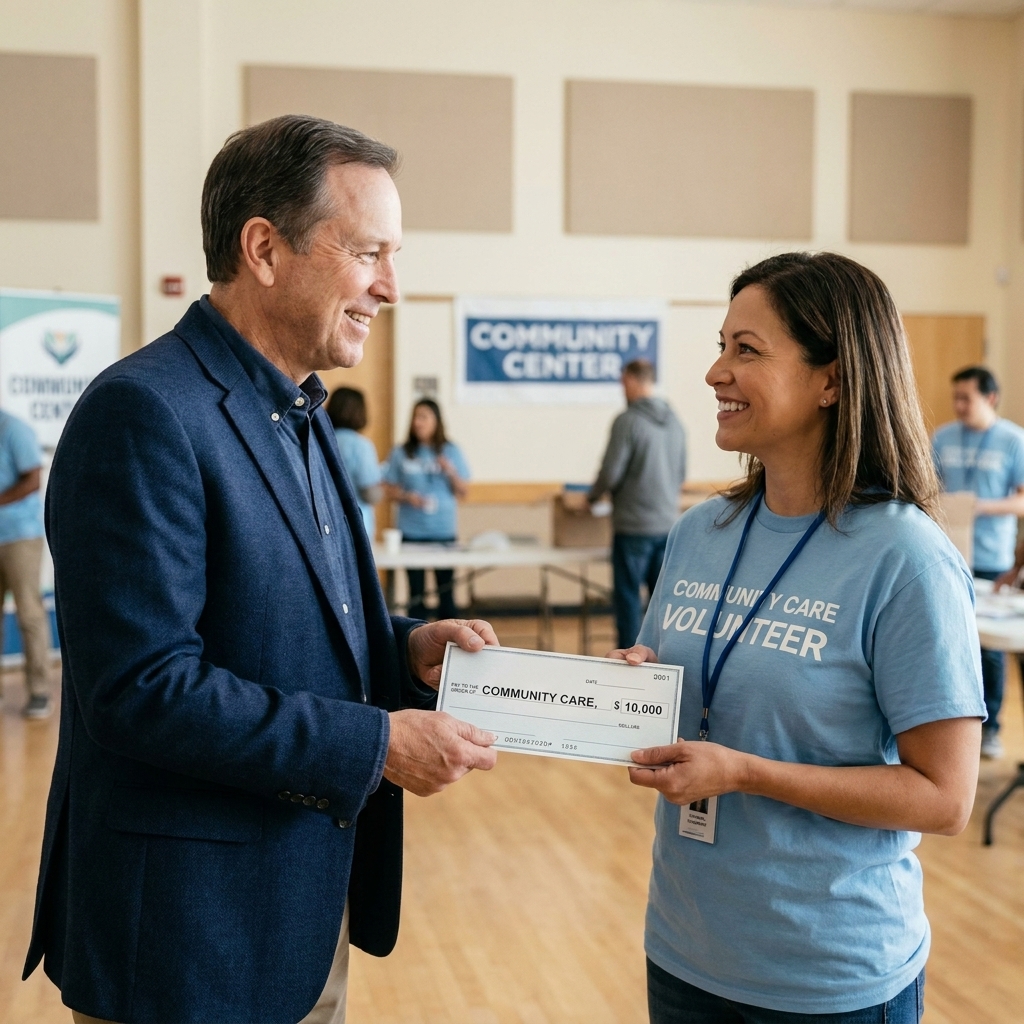
If you are charitably inclined, a qualified charitable distribution (QCD) can be one of the cleanest tax moves in retirement.
Key basics to know:
- You must be age 70½ or older to do a QCD.
- QCDs come from IRAs (not most active 401(k) plans unless you roll funds to an IRA first).
- The QCD limit used to be $100,000 and is now indexed for inflation. The cap changes over time, so confirm the current-year limit before you act.
- QCDs generally cannot go to donor-advised funds or private non-operating foundations.
Done correctly, a QCD can count toward your RMD but does not show up in your AGI.
Why that matters: a lower AGI often means lower provisional income, which can reduce how much of your Social Security is taxed.
This is a do-it-right-the-first-time strategy. The donation must go directly from the IRA custodian to the charity. If you like this idea, it is worth confirming the steps with your custodian and tax pro before you push the button.
7) Plan for income spikes
A lot of Social Security taxation pain comes from one-time spikes that push provisional income way above the thresholds for a single year.
Common culprits:
- Selling a second home or investment property
- A large IRA withdrawal for a car, roof, or helping family
- Cashing out savings bonds
- Taking a big pension lump sum (when available)
Some income spikes are unavoidable, but many are adjustable. If you can choose the year, you can sometimes reduce Social Security taxes by:
- Coordinating the event before you claim benefits
- Splitting withdrawals across two tax years
- Using a blend of taxable and Roth dollars rather than one large taxable withdrawal
I like to think of it this way: surprises are expensive. A little calendar planning can save real money.
Quick checklist
- Estimate your provisional income for this year using last year’s return as a starting point.
- List income sources you can control (IRA withdrawals, Roth withdrawals, capital gains).
- Identify one lever to pull before year-end: a smaller IRA withdrawal, a different account choice, or a delayed sale.
- If you give to charity, ask whether QCDs fit your situation.
FAQ
Can I avoid taxes on Social Security completely?
Sometimes, yes, especially if your only income is Social Security or you have modest other income. For many retirees, the realistic goal is not zero tax. It is reducing how often you hit the 85% taxable range and keeping your lifetime tax bill lower through smart timing.
Does claiming later reduce tax on benefits?
Delaying can help in two ways: (1) it may give you years to do Roth conversions or capital gain planning before benefits start, and (2) you might have fewer years where Social Security overlaps with large RMDs. But delaying is not automatically a tax win for everyone. It is a claiming decision first, then a tax decision.
Will these strategies affect Medicare premiums?
Some can. Higher income, including Roth conversions and large capital gains, can increase Medicare premium surcharges (IRMAA). Also note that IRMAA is based on your MAGI from two years prior, so a high-income year can affect premiums later.
Should I talk to a tax professional?
If you are doing Roth conversions, selling property, taking large withdrawals, or using QCDs, it is smart to coordinate with a CPA or enrolled agent. The strategies are legal and common, but the details matter.
Bottom line
Social Security taxation is not a punishment, but it can feel like one when it shows up unexpectedly. The fix is usually not complicated. It is about keeping provisional income under control with smart timing, smart withdrawals, and a plan for the big years.
If you want help pressure-testing your own numbers, start with a simple question: Which income sources can I control this year? That one question is where most tax savings begins.