Step-by-step tips to claim your full employer match, avoid common mistakes, and use vesting rules and contribution timing to accelerate retirement savings.
Most retirement goals are so big they feel like trying to “boil the ocean.” Save $800,000. Build a “comfortable” nest egg. Replace 70% of income. It is no wonder so many smart, hardworking people freeze up and do nothing.
Instead, let’s do what works in real life: break the mission into mini-milestones you can actually see and celebrate. Think of it like a road trip. You do not stare at the final destination for six hours. You focus on the next turn, the next town, the next refill.
Below are seven mini-milestones that “gamify” retirement saving without turning it into a gimmick. Each one comes with a clear target, why it matters, and the next move once you hit it.
How to use these milestones
- Pick one milestone at a time. Your job is not to do all seven this month.
- Name your milestone. “Get the match” or “First 10K” feels more real than “save more.”
- Track it somewhere you will see weekly. A sticky note, a phone note, or a simple spreadsheet is enough.
- Celebrate wins responsibly. A nice dinner is fine. A new car payment is not.
One quick note before we dive in: the best milestone is the one that removes stress first. If you have high-interest debt or no emergency buffer, start there. Retirement is a long game, but life happens in the short term.
Mini-milestone #1: Set autopilot
The goal
Set an automatic contribution to your 401(k), 403(b), or IRA that you can keep for at least six months, even if it is small.
Why it matters
The biggest retirement “hack” is consistency. Autopilot turns saving from a monthly decision into a background habit, like your phone bill.
Make it actionable
- If you have a workplace plan, set a percentage per paycheck.
- If you are using an IRA, set a monthly auto-transfer from checking.
- Start with what is realistic and increase later. A steady 3% beats a heroic 15% you quit in two paychecks.
- If you get stuck on investments, choose a simple default like a target-date fund or a broad, low-cost index fund option and keep moving.
Level up after you win
Set an automatic increase: +1% every three to six months, or whenever you get a raise.
Mini-milestone #2: Get the full match
The goal
Contribute enough to your workplace plan to receive 100% of your employer match.
Why it matters
This is one of the few moments in personal finance where you can get an immediate boost that is very hard to beat. For example, if your employer matches 50% of what you contribute up to 6% of your pay, contributing 6% typically gets you an extra 3% of pay from your employer.
One important caveat: match rules are not identical everywhere. Some plans have vesting schedules, eligibility requirements, or a year-end “true-up.” It is worth confirming the fine print so you do not accidentally miss out.
Make it actionable
- Find your match formula in your benefits portal or summary plan information.
- If you are not sure, ask HR or payroll: “What percent do I need to contribute to get the full match, and are there vesting or true-up rules?”
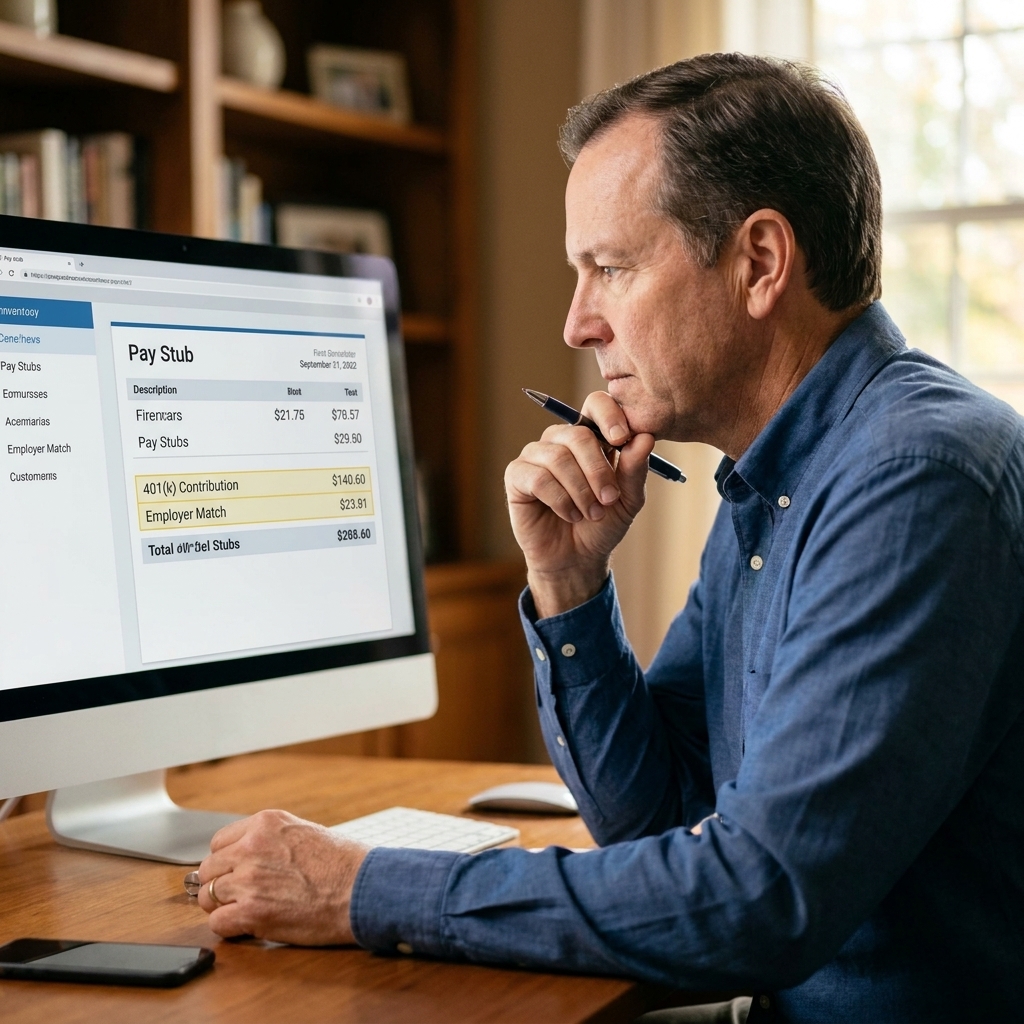
- Check your paystub to confirm the match is actually showing up.
Level up after you win
Increase contributions by 1% and aim for the next milestone: building a cushion so you do not raid your retirement plan when life gets messy.
Mini-milestone #3: Build a starter buffer
The goal
Save $1,000 to $2,000 in a separate high-yield savings account.
Why it matters
This buffer keeps small emergencies from turning into credit card debt or, even worse, a 401(k) loan or early withdrawal. In my years in HR, I saw it over and over: a car repair becomes a retirement setback.
Make it actionable
- Open a savings account that is not your everyday checking bank, so you are less tempted to dip in.
- Automate even $25 to $100 per paycheck until you hit the target.
- Keep it boring. This money is a shield, not an investment.
- Quick reality check: rates change, so focus on access and consistency. Also make sure your account is FDIC or NCUA insured and you stay within coverage limits.
Level up after you win
Work toward a fuller emergency fund (often three to six months of core expenses). But you do not need to perfect this before making retirement progress. You are building layers of security.
Mini-milestone #4: Fund an IRA target
The goal
Contribute the annual maximum to an IRA, or set a clear annual target if maxing out is not realistic yet. (Check the current-year IRS limit, especially if you are age 50 or older.)
Why it matters
An IRA gives you more control. You can choose Traditional or Roth (depending on your tax situation and eligibility) and you are not limited to your workplace plan lineup.
Make it actionable
- If you can max it: divide the annual limit by 12 and automate that monthly amount.
- If you cannot: set a milestone like “$3,000 this year” or “$250 a month.”
- Remember the fine print: Roth IRA eligibility and Traditional IRA deductibility can depend on income and whether you are covered by a workplace retirement plan.
- Choose a simple, diversified investment option you understand, like a target-date fund or a total-market index fund, then stop tinkering.
Kitchen-table rule of thumb: If you expect your tax rate will be higher later, Roth can be appealing. If you need the tax break now, Traditional may help. When in doubt, focus on contributing something and refine later.
Level up after you win
Once your IRA target is on autopilot, go back to your workplace plan and bump your percentage.
Mini-milestone #5: Reach $10,000
The goal
Get to $10,000 in your retirement accounts combined.
Why it matters
Your first $10,000 is a momentum milestone. Early on, growth looks slow because most of the balance is your contributions. This milestone proves the system works and helps you stick with it long enough for compounding to matter.
Make it actionable
- Total up balances across 401(k), 403(b), IRA, and old plans.
- Track the combined number monthly, not daily.
- Focus on contribution rate and consistency, not trying to pick “the best” fund every week.
Level up after you win
Schedule a one-time “cleanup check”: confirm your beneficiary designations are correct and your investments match your risk comfort level. If you have old 401(k)s, consider consolidating them with a rollover so they are easier to track, and avoid cashing them out when you change jobs.
Mini-milestone #6: Match + 5%
The goal
Contribute enough to your workplace plan to get the full match plus an additional 5% of your pay.
Why it matters
This is where retirement saving starts to feel like a real engine, not a token effort. For many people, match plus 5% is a strong, realistic step that moves the needle without blowing up the budget.
Make it actionable
- If your match requires 4%, aim for 9% total.
- If your match requires 6%, aim for 11% total.
- Use “raise days” to increase your percentage so your paycheck does not feel smaller.
Level up after you win
If you are age 50 or older, consider whether catch-up contributions fit your budget. Even small increases can have a big impact when retirement is closer.
Mini-milestone #7: Hit $100,000
The goal
Reach $100,000 invested across all retirement accounts.
Why it matters
This is the milestone people talk about for a reason. At $100,000, the market’s normal ups and downs can move your balance by thousands in a year. That can feel scary, but it also means compounding is starting to carry more of the load.
Put simply: the first $100,000 can feel like pushing a heavy cart uphill. After that, the cart still needs steering, but it starts rolling.
Make it actionable
- Track contributions and balances quarterly, not constantly.
- Rebalance with a simple rule, not a feeling. For many people, that looks like once a year or when your mix drifts meaningfully from your target.
- Keep fees low and diversification high.
Level up after you win
Shift from “saving mode only” to “full plan mode.” That means estimating a retirement income target, thinking through Social Security timing, and mapping out withdrawal strategy and taxes. You do not need to solve it all today, but you are ready for the next chapter.
Make it feel like a game
- Use streaks: “12 straight months of contributions” is a win you control, even in a down market.
- Use checkpoints: Review contributions on your birthday or at tax time.
- Use rewards: When you hit a milestone, treat yourself to something that does not create a monthly bill.
- Use guardrails: If markets drop, your milestone is “keep contributing,” not “fix it by trading.”
Common questions
What if I am starting late?
You are not alone, and you are not broken. Late starters can make meaningful progress by focusing on the levers that matter: contribution rate, consistency, and avoiding costly mistakes like cashing out accounts when changing jobs. Mini-milestones are especially powerful here because they replace shame with momentum.
Should I pay off debt first or save for retirement?
If it is high-interest credit card debt, prioritize knocking that down aggressively while still contributing enough to get your employer match if you have one. For lower-interest debt, you can often do both by setting clear targets for each.
How often should I check my retirement accounts?
For most people, monthly is plenty, and quarterly is even better once you are steady. Daily checking turns normal market movement into unnecessary stress.
Is $100,000 the magic number everyone needs?
It is a motivation milestone, not a finish line. Your real number depends on your spending needs, Social Security, pension income (if any), health costs, and retirement age. The point is to build the habit and the base so planning gets easier.
Your next step
- If you do nothing else today, set or raise your automatic contribution by 1%.
- If you already contribute, confirm you are getting the full employer match and understand the vesting or true-up rules.
- If surprises keep derailing you, start the $1,000 buffer.
Retirement saving does not require perfection. It requires a plan you can live with. Stack a few small wins, and you will be surprised how quickly “someday” starts looking like a real date on the calendar.